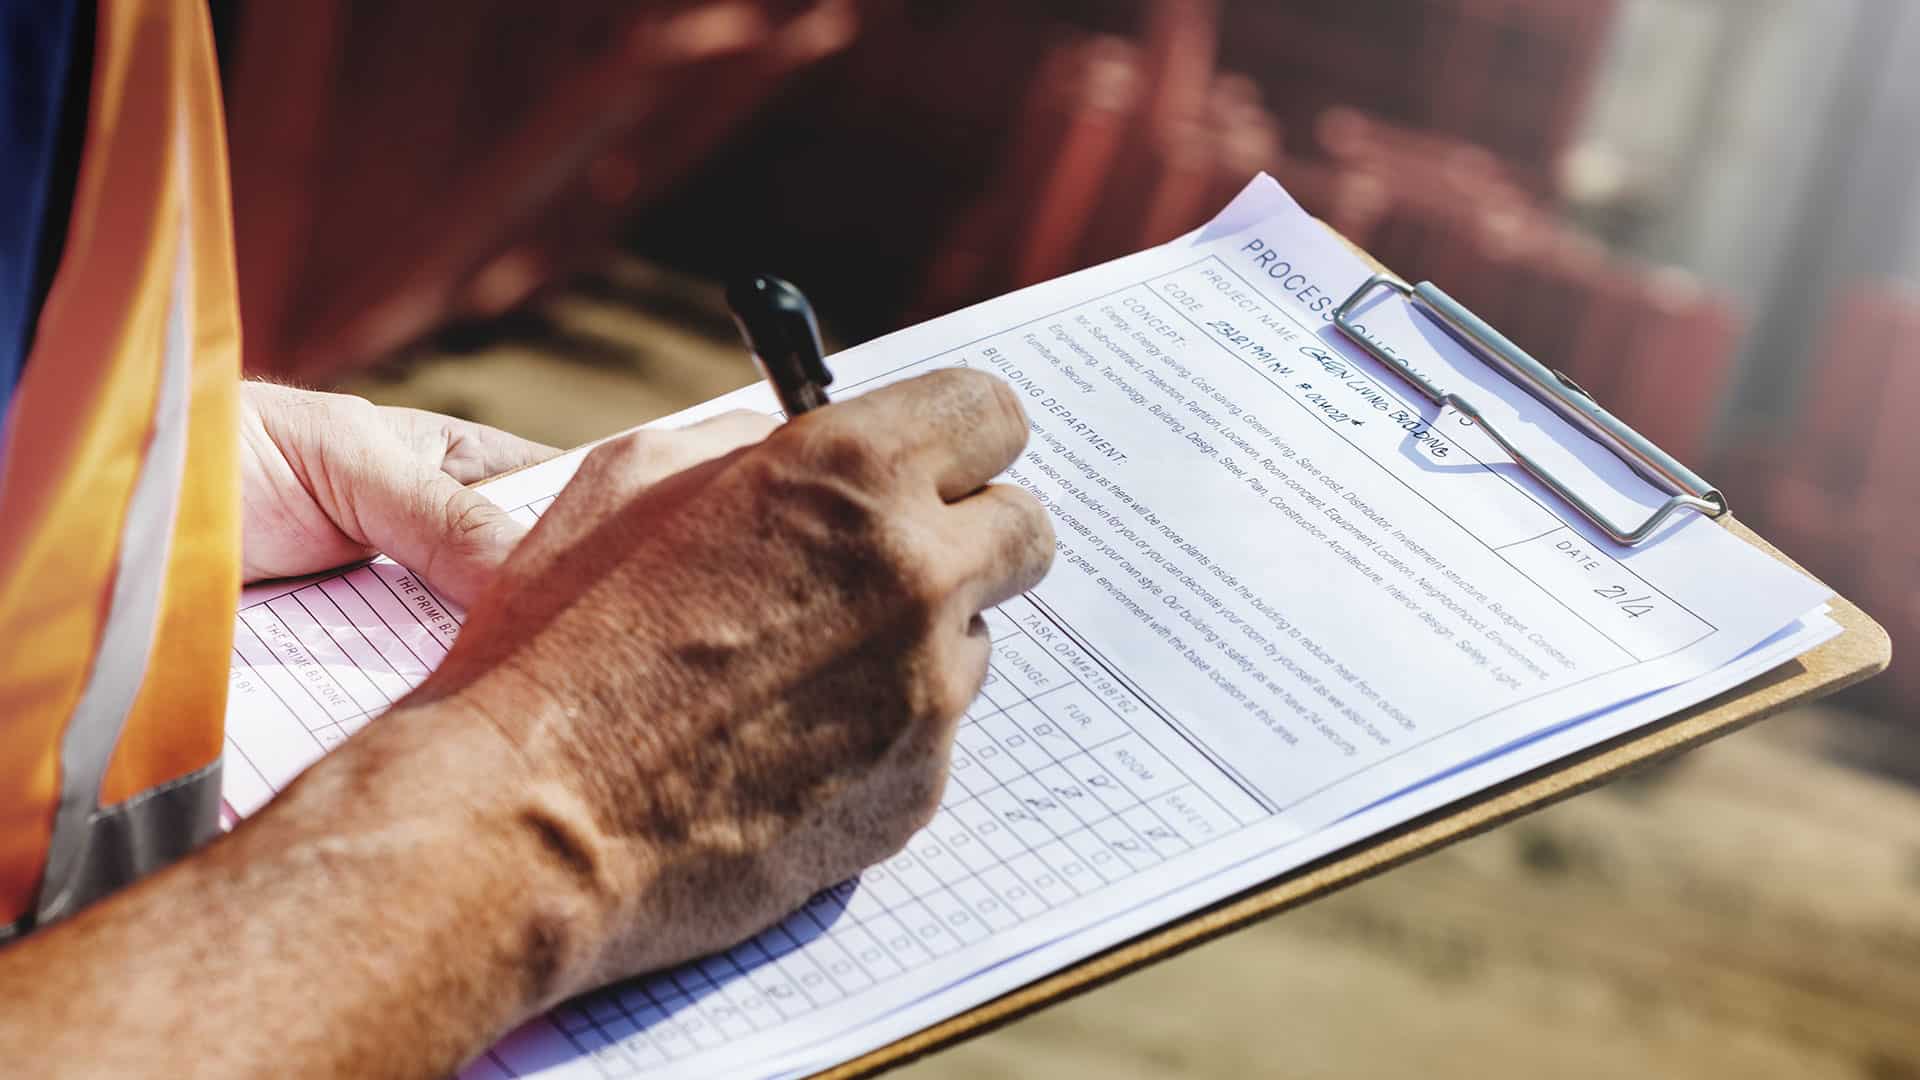

When you are buying a property in Harrogate, arranging the right house survey can help you understand more about its condition before you become legally committed to the purchase.
A survey can identify issues that may not have been obvious during a viewing, from problems requiring relatively straightforward repairs to defects that could involve considerably more work.
The type of survey you choose will usually depend on the age, condition and construction of the property you are buying.
This can be particularly important for a first time buyer who has limited experience assessing the condition of a property.
Harrogate also has a varied housing stock, including period properties, traditional terraces, converted properties and newer homes, so the level of survey suitable for one purchase may not be appropriate for another.
It is also important to understand the difference between a house survey and the mortgage valuation arranged by your lender.
They serve different purposes, and relying on a mortgage valuation alone may not give you the information you want about the condition of your new home.
What Are the Different Types of House Survey?
Residential property surveys are commonly provided at three levels, with the appropriate choice depending on how much detail you need about the property.
A RICS Home Survey Level 1 provides a basic overview of the property’s condition. It uses a straightforward format to highlight the condition of different parts of the building and identify significant issues that require attention.
As the least detailed of the three levels, it may be more appropriate for a conventional property that appears to be in good condition.
A RICS Home Survey Level 2 provides more detail. It includes an inspection of the property and reports on defects that could affect it, alongside information that can help you understand repairs and ongoing maintenance.
This type of survey is commonly considered for conventional properties that appear to be in reasonable condition.
A RICS Home Survey Level 3 provides the most detailed assessment. It looks more closely at the property’s construction and condition, describes identifiable defects and can provide information about the scope of repairs required.
This may be worth considering for an older property, a home in poor condition, an unusual building or somewhere you intend to renovate substantially.
The level number should not be chosen purely on the property’s purchase price. A relatively inexpensive older home requiring extensive work could warrant a more detailed survey than a higher-value modern property in good condition.
Is a Mortgage Valuation the Same as a House Survey?
No. This is an important distinction when you are buying with a mortgage.
A mortgage lender may arrange a valuation as part of assessing the property you want to buy. Its primary purpose is to help the lender establish whether the property provides suitable security for the mortgage and whether its value supports the lending requested.
The valuation is carried out for the lender’s purposes. Depending on the lender and property, it may be relatively limited and may even be completed without a traditional physical inspection.
A house survey is different. You arrange it for your own benefit to obtain information about the condition of the property.
This distinction can be especially useful for a first time buyer in Harrogate to understand. Receiving a satisfactory mortgage valuation does not mean a detailed assessment has been carried out on the roof, walls, damp, services or other aspects of the property’s condition.
Your mortgage valuation and your chosen house survey can therefore form separate parts of the buying process.
What Happens if the Survey Finds Problems?
It is common for a house survey to identify some issues, particularly when you are buying an older property. Finding defects does not automatically mean you should withdraw from the purchase.
The nature and severity of the problem are more important.
Some findings may relate to routine maintenance that you can budget for after moving in. Others could indicate more significant work and lead you to seek further information from an appropriate specialist before proceeding.
If the survey identifies an unexpected problem that could be expensive to rectify, you may decide to discuss the findings with the seller or estate agent.
Depending on the circumstances, this could lead to further investigation or negotiations over the agreed purchase price.
A seller is not required to accept a lower offer simply because a survey has identified work. You will need to decide whether you remain comfortable proceeding at the agreed price and with the potential cost of any repairs.
The survey can therefore give you more information at an important stage of the purchase, before you become legally committed at exchange of contracts.
Arranging Your Mortgage and Survey When Buying in Harrogate
Your house survey and mortgage are separate, although both can be important when you are progressing with a property purchase.
As a mortgage broker in Harrogate, our role is to deal with the mortgage side of your purchase. Our mortgage advisors can look at your circumstances, search the lenders we work with, and progress your mortgage application once you have found a property.
Your lender will deal with its mortgage valuation as part of the application where required. If you want a more detailed assessment of the property’s condition, you can separately arrange the appropriate house survey.
For first time buyers in Harrogate, understanding this difference can prevent the lender’s valuation from being mistaken for a survey carried out on your behalf.
The right survey will depend on the property itself. Its age, condition, construction and any renovation work you are considering can all influence whether a Level 1, Level 2 or Level 3 survey is appropriate.
Taking the time to choose a suitable survey can give you a clearer picture of the property you are buying while our mortgage advisors progress the financial side of your purchase.
Date Last Edited: August 20, 2026